Author: Hayden Richards

  • Director Mortgage Accounts: Why Do Company Profit and Drawings Differ for UK Lenders?

    Director Mortgage Accounts: Why Do Company Profit and Drawings Differ for UK Lenders?

    Director mortgage accounts help explain why UK mortgage lenders distinguish taxable personal drawings from retained company net profits: salary and dividends reach the director personally, while retained profit stays in the company after expenses, tax, debts and cash-flow needs. Specialist underwriters assess the chosen income method, ownership share, business sustainability and evidence against their criteria.

    Hayden Richards, CeMAP — Senior Mortgage & Protection Specialist

    Mortgage Accounts | Director Mortgage Accounts: Why Do Company Profit and Drawings Differ for UK Lenders?

    What is the difference between company profit and director drawings for a mortgage?

    Company profit and director drawings are different figures. Salary is paid to a director through payroll, while dividends are distributions to shareholders from profits available for distribution. Both can form part of the director’s personal income, but the company’s net profit is calculated before deciding how much, if any, to distribute.

    Retained profit remains in the business rather than automatically becoming the director’s personal income. The company may need to meet tax bills, repay debts, pay operating costs or maintain working capital, so the full accounting profit may not be available to draw.

    A director’s access to company profit also depends on their shareholding and the company’s obligations. If other shareholders own part of the business, the entire profit cannot simply be treated as one applicant’s income.

    Can you get a mortgage as a company director? Yes, but the affordability assessment depends on the lender’s criteria and the evidence supporting personal income or eligible company profit. Our guide to mortgages for limited company directors explains why different lenders can reach different assessments from the same accounts.

    A strong company bank balance on its own does not establish what the director can personally afford to repay. Underwriters need to understand both the business’s position and the income available to the applicant.

    How do UK mortgage lenders assess salary and dividends versus retained profit?

    Some lenders assess salary plus dividends shown in personal tax evidence. Others may consider salary plus the director’s share of net profit, which can produce a different affordability figure when the company retains profit rather than paying it out.

    Retained-profit assessment is not automatic. A specialist underwriter may consider the director’s ownership, the company’s performance, its obligations and whether using some profit for personal borrowing is consistent with the business’s ongoing financial needs.

    The table summarises common assessment approaches, not rules that apply to every lender. The documentation and limitations vary, so confirm which method a lender will use before relying on an affordability estimate.

    Comparison Salary + Dividends Salary + Share of Net Profit Director Loan / Drawings
    Assessment Method Salary and dividends received personally Salary plus the applicant’s eligible share of company net profit Review of director loan movements and drawings, not treating a loan as earnings
    Lender Type High-Street Banks Specialist Mortgage Lenders Commercial / Private

    The Limited Company Director Mortgage service is relevant when comparing these approaches because specialist lenders may assess salary, dividends, a share of net profit or retained profits. The method used still depends on the lender’s criteria and the evidence presented.

    For a lender-by-lender view of how assessment methods differ, use a lender comparison matrix that considers income structure alongside trading history and company evidence. A method that suits one director’s accounts may not suit another’s.

    An open ledger, calculator and mortgage paperwork arranged on a white office desk, with a grey London skyline beyond the

    Why do high-street banks decline directors who leave profit in their business?

    Where a lender bases affordability mainly on personal income, retained reserves may not increase the figure used in its assessment. The director has not received those funds as salary or dividends, so the company’s profit can look strong while the income shown in personal tax records remains comparatively low.

    Some specialist lenders may assess an eligible share of net profit or retained profit instead. They still examine the company’s financial position, the director’s ownership and whether profits are sustainable, rather than treating every pound in the accounts as personal income.

    Taking extra dividends solely to raise a mortgage income figure can have tax and business consequences. It also does not ensure that a lender will assess the new drawings in the way the director expects, so discuss the wider implications with an accountant before changing how income is taken.

    Our guide to director retained-profit mortgages focuses on accumulated company reserves and how some specialist assessments may take them into account. It helps explain why retained reserves and personal drawings should be presented as separate parts of the affordability picture.

    bd6a7c73 1097 4cb0 b036 daf04eccef20
    Did You Know?
    The average UK loan-to-income ratio for mortgage sales overall was 3.5 in 2025.

    Which documents prove director drawings and company profit to underwriters?

    Prepare personal income evidence and company evidence separately: they support different parts of the assessment. Personal documents may show taxable salary and dividends, while company records show profit, liabilities and recent trading.

    • Personal income: SA302 tax calculations, Tax Year Overviews, payslips and dividend vouchers.
    • Company performance: finalised company accounts and, where relevant, an accountant’s certificate or reference.
    • Recent trading: management accounts and business bank statements to explain current performance, cash flow or a change since the last completed accounts.
    • Director’s loan account: a record of movements, the balance and any repayment arrangements.

    SA302s and Tax Year Overviews provide evidence of figures submitted for personal tax purposes. HMRC provides information and services relating to these records through its official website.

    Management accounts can help explain what has happened since the latest finalised accounts, but they are current-period figures, not a replacement for completed accounts. If filed accounts, management figures and bank activity differ, ask the accountant to reconcile the periods and explain the reasons clearly.

    For example, an apparent change may relate to when income or costs were recorded, a shift in the company’s year-end, or a change in cash flow. Give the underwriter a consistent timeline rather than submitting figures that appear to contradict one another.

    A director’s loan account is not earned income. An overdrawn balance may affect the director’s personal liabilities and the company’s cash position, so explain its current balance and repayment clearly rather than presenting it as salary or dividend income.

    The Director Logic Check analyses salary, dividends and company performance against lender criteria using the latest accounts or estimates. It is relevant when figures need to be assessed together before an application is prepared.

    A wide view of a contemporary British home at dusk, with a closed financial folder and keys on a foreground table suggesting

    How does corporate shareholding percentage determine allowable borrowing?

    Shareholding can affect whether a lender treats an applicant as a director with influence over company income or assesses them more like an employee. Lenders use different criteria and thresholds, so establish how the applicant’s ownership will be classified before interpreting an affordability figure. The limited company director mortgage FAQ also covers director classification.

    Where a lender assesses a share of net profit, the applicant’s ownership proportion matters. The underwriter also considers company debts and obligations, and whether the profit appears sustainable, because the accounting figure alone does not show how much is available to support personal borrowing.

    For a recently incorporated business, a conversion from sole-trader status or a short trading history, organise the evidence into a timeline. Include earlier accounts, current performance and relevant industry experience, with contracts or accountant-supported projections where they help explain the business’s position.

    Projections and contracts can provide context, but they do not replace the lender’s required evidence. Explain how the business moved from its previous structure to the current company, and ensure the dates and income figures align across the documents.

    Losses or falling profits can weaken the affordability picture even when personal drawings appear stable. Set out the trend and any material changes using consistent figures so that an underwriter can assess the direction of the business as well as its latest result.

    Director mortgage accounts can therefore depend on more than the amount drawn personally. Ownership, trading history and the company’s ability to sustain its profits all influence which evidence and assessment method may be relevant.

    Did You Know?
    The UK median loan-to-value ratio for first-time buyers was 85.6% in 2025.

    See also: Self-Employed Mortgages UK – Sole Traders, Directors & Contractors, Contractor Mortgages, Complex Cases, Complex Income, One Year Accounts Mortgage, Buy a House Through a Limited Company – Business Owner Mortgages UK, Overseas Income, Foreign National Complex Income Mortgage Advice, Dual Income Households, Cis Contractor Mortgage, Ir35 Contractor Mortgage, Zero Hours Contract Mortgage, Portfolio Landlord Mortgage, Foreign National Mortgage, Self Employed Mortgage Faq, Director Salary and Dividend Mortgage FAQ – How UK Lenders Assess the Mix, Day Rate Contractor Mortgage Faq, Ir35 Mortgage Faq, Umbrella Company Mortgage Faq, Mortgage Underwriting Faq, Contractor Mortgages, Cis Worker Mortgages, Mortgage Without Payslips Faq, Freelancer Mortgage Faq, Overseas Income Mortgage Faq, Expat Mortgages Uk.

    Two account statements showing company profit and personal drawings lie side by side on a stone office table, with a blurred

    Frequently asked questions about director mortgage accounts

    Can you get a mortgage if you are a director of a company?

    Yes, a company director can apply for a mortgage, and the lender will assess the full application rather than the job title alone. The outcome depends on its income criteria, household commitments, credit history and the property being purchased, together with evidence that supports the director’s stated income.

    Can a director apply for a mortgage before the first full set of company accounts is filed?

    In some cases, a lender may consider an application before the first full accounts are filed, but it will need other evidence to understand the business. An accountant’s information, current trading records and relevant contracts may help explain the case, while the lender decides whether those materials meet its requirements.

    How can a changed company year-end affect a director’s mortgage application?

    A changed year-end can leave accounts covering periods of different lengths, making direct year-on-year comparisons less clear. Ask the accountant to set out the dates each set of accounts covers and reconcile the periods so that the underwriter can distinguish a genuine change in performance from a difference in accounting period.

    Can a partner’s PAYE income be combined with a director’s income for a mortgage?

    Yes, a joint application can include a partner’s PAYE earnings alongside director income if the lender accepts both applicants and their respective evidence. The lender assesses the applicants’ combined income and commitments under its criteria, so the partner’s payslips do not change how the director’s company figures are assessed.

    Can a director use accounts from a sole-trader business after incorporating?

    Earlier sole-trader accounts may help explain the business’s trading history after incorporation, particularly where the activity and customers continued under the company. The underwriter will need a clear account of what changed at incorporation, which assets or contracts transferred, and how the old and new figures relate without treating the two legal structures as identical.

    For more detail on retained-profit evidence and lender questions, see our frequently asked questions about director retained-profit mortgages.

    What should directors prepare before discussing a mortgage?

    Start by separating personal taxable drawings from company profit, then identify which assessment method fits the accounts and ownership structure. Reconcile personal tax records, finalised accounts, current management figures and business banking before relying on an affordability estimate.

    Director mortgage accounts can produce different outcomes with different lender criteria. An accountant can help make the financial records consistent, while a mortgage adviser can assess which evidence and income method may be relevant to the application.

    Mortgage advice is regulated in the UK. Consumers can use the Financial Conduct Authority website to find information about financial services and regulation.

    YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.
    The guides and articles on this website are provided for general information only.
    Mortgage advice is provided by Hayden Richards, CeMAP-qualified, as a Registered Individual of Marklay Mortgages Ltd, authorised and regulated by the Financial Conduct Authority (FRN 930490). Richards & Logic is a trading style of MarketMedia Ltd (07765565).

    Related guides: Specialist Director Mortgage Broker Guide for Limited Company Directors in 2026 · Top Mortgage Options for Professional Contractors and Consultants in 2026
  • Remortgaging with Complex Income: How UK Lenders Assess Your Application

    Remortgaging with Complex Income: How UK Lenders Assess Your Application

    Remortgaging with Complex Income: How UK Lenders Assess Your Application

    Remortgaging with complex income means showing how each income source is earned, evidenced and likely to continue. A product transfer with your current lender and a remortgage to a new lender can involve different assessments.

    This is general information, not personal advice.

    Remortgaging Complex Income | Remortgaging with Complex Income: How UK Lenders Assess Your Application

    What counts as complex income when you remortgage?

    Complex income can include overtime, commission, bonuses, several income sources, self-employed earnings, company-director income and contractor pay. These sources may vary in amount or be evidenced in different ways, so lenders can assess each under different criteria.

    For a full remortgage to a new lender, expect an assessment against that lender’s affordability and underwriting criteria. A product transfer, which means changing your mortgage deal with your existing lender, may follow that lender’s own process. Both routes can involve different income checks, particularly if you are asking to borrow more.

    The remortgage complex-income FAQ explains how the route can affect an application. For a wider explanation of income, affordability and lender decisions, see the UK mortgage underwriting FAQ.

    How variable and additional income may be assessed

    For overtime, commission and bonuses, lenders may consider the payment pattern, how consistently the income has been received and whether it appears sustainable. An occasional payment can be treated differently from ongoing income. A lender may average variable pay or use only a proportion of it, but the method depends on the lender, income type and evidence.

    The Bonus Income Mortgage FAQ covers how lenders may assess bonus calculations, payment timing, supporting evidence and discretionary awards. It is relevant if a bonus forms part of your affordability picture, because the amount paid and its pattern can matter as much as the headline figure.

    Commission should be shown as income actually received, not simply as potential earnings in a remuneration plan. For commission, the Commission Income Mortgage FAQ sets out the evidence and calculation approaches lenders may use. Overtime is another variable source; the overtime income guidance covers how its pattern may be assessed.

    Rental, pension, investment and benefit income may be considered where relevant. The treatment depends on the source, its continuity and the lender’s criteria. When income comes from PAYE, freelance, rental or dividends, lenders may assess the combination differently from a single salary; the multiple-income-sources FAQ sets out evidence and assessment for different income streams.

    Separate regular contractual pay from discretionary or irregular earnings. That gives the lender a clearer account of the income available for mortgage repayments and avoids presenting occasional bonus, overtime or commission as dependable future income.

    A contemporary British townhouse with a subtle home-office window, photographed alone in soft overcast light, its clean

    How lenders assess self-employed people, directors and contractors

    For a sole trader, lenders may assess taxable profit shown in accounts or tax records. Turnover is the business’s revenue before costs; it is not the same as personal income available for mortgage repayments.

    For a limited company director, distinguish salary and dividends from company turnover and retained profits. Company accounts and personal tax records can help show how the figures relate. Some lender criteria may allow retained profits to be considered in particular circumstances, but money held in a company is not automatically treated as personal income.

    A director remortgage therefore needs a clear explanation of how income is drawn and what remains in the company. The figures on company accounts, tax calculations and personal bank statements may differ because they record different things.

    A day-rate contractor, a fixed-term contractor and someone working through a limited company or umbrella company have different working arrangements. Lenders may assess a contractor’s income using the contract structure and evidence of ongoing work; they may use an annualised day rate in some cases. An applicant’s IR35 position can also relate to how the work is structured, so keep the description consistent rather than combining different contractor categories.

    Contractors working through a limited company, umbrella company or fixed-term contract are the focus of the Contractor mortgages FAQ. It suits this part of the assessment because it distinguishes those arrangements and explains why the contract and income evidence matter. For every category, trading-history requirements and income calculations vary by lender.

    How affordability, outgoings and borrowing amount fit together

    Lenders typically assess income alongside household spending, credit commitments and other financial responsibilities. These affect the amount available for mortgage repayments. They may also assess creditworthiness and the property being mortgaged, so a high stated income alone does not determine borrowing capacity.

    Lenders may consider gross income supported by payslips, accounts or tax records. Their affordability assessment also takes account of tax, regular spending and commitments. Gross income is therefore not the same as the amount left to meet mortgage payments.

    If you request additional borrowing or equity release through a remortgage, the total loan and property value determine the loan-to-value (LTV) calculation. Affordability and LTV are separate considerations: a requested amount may fit one measure but still be outside the lender’s affordability assessment or other criteria. LTV limits vary by lender and are subject to change.

    Repayment and interest-only mortgages have different repayment structures. With a repayment mortgage, regular payments cover interest and reduce the amount borrowed over the term. With interest-only borrowing, the capital remains outstanding, so the lender also assesses the proposed repayment strategy alongside affordability.

    An empty professional office meeting table holds neatly organised income documents and a calculator, with a softly blurred

    What evidence can support a complex-income application?

    Do you have to prove income when remortgaging? For an application to a new lender, expect to provide evidence that supports the income and affordability figures. The documents requested vary with the income source and the lender’s process.

    Commonly requested records include payslips, bank statements, tax returns, SA302 tax calculations, tax year overviews and business accounts. A lender may also ask for a current contract, an accountant’s reference or other evidence relevant to your work. For presenting income structure, retained profits, dividends and contractor earnings, see the self-employed mortgage advice page. It is relevant when your personal and business figures need to be read together.

    For a sole trader or company director, use records that distinguish personal income from business turnover, profit and retained funds. Explain how salary, dividends or drawings relate to the figures in the accounts and tax records. The self-employed mortgage FAQ covers commonly requested tax, account and bank records.

    For variable pay, arrange the available evidence so the timing and pattern of overtime, commission or bonuses are clear. A single unusually high payment does not show whether the income is recurring. If payslips, bank statements, accounts and tax records show different totals, explain the timing, deductions or income category behind the difference and keep the application figures consistent.

    For a comparison of how lender criteria can differ across complex-income types, consult the lender comparison matrix. Criteria can change, so a comparison is a starting point for understanding assessment methods, not a substitute for checking the relevant lender’s current requirements.

    How income changes and future stability can affect the assessment

    A recent fall in income can reduce the amount a lender considers affordable. Explain why the change occurred and support your current position with relevant evidence; higher past earnings alone may not represent the income available now.

    A history of variable income can help show its pattern, but lenders may also consider whether it is likely to continue and whether expected changes could affect your ability to maintain repayments. Disclose a new role, a gap between contracts or a change in business earnings. Unexplained differences make the income picture harder to assess.

    Do not present occasional bonuses, overtime or commission as dependable future income. Set out what you have received, how often it has been paid and whether there is evidence it may continue.

    If you have a short trading history, the guidance on applying with one year of self-employed accounts explains why lenders may assess continuity, trading history and the supporting evidence differently.

    A modern British apartment building at blue hour, warmly lit windows contrasting with a cool city skyline, seen from a quiet

    How to prepare and compare remortgage options

    Before comparing routes, write down each income source, the evidence supporting it, regular outgoings and credit commitments. That gives you a consistent account to use when a lender asks how the figures were calculated.

    Compare the amount you want to borrow and the total costs involved. Include product fees and any early repayment charge (ERC) on your existing mortgage. These costs can affect whether a new deal or additional borrowing makes sense; do not judge an option by its headline interest rate alone.

    Ask how the proposed route treats your specific income structure and any additional borrowing. A self-employed remortgage in the UK, a contractor remortgage and an application with several income sources can each raise different evidence questions. Lender criteria and assessment methods vary.

    When a broker may be useful

    A broker experienced in complex income may be useful where your accounts, contracts and personal income figures need to be reconciled before an application is submitted. The process should begin with a feasibility assessment: validate the figures, identify questions an underwriter may raise and decide which lender criteria fit the case. The complex-cases page explains the type of cases covered.

    Common pitfalls

    • Assuming every lender treats variable or secondary income in the same way.
    • Confusing business turnover or company profits with personal income available for repayments.
    • Leaving out an income source, credit commitment or unusual transaction that needs explaining.
    • Relying on a single high payment to represent ongoing variable income.
    • Starting a new-lender application without checking fees and any ERC on the existing mortgage.

    Practical checklist

    • List each income source and separate contractual pay from variable or discretionary earnings.
    • Gather the relevant payslips, bank statements, tax records, accounts and contracts.
    • Reconcile differences between personal and business records, and explain the reason for them.
    • Set out regular household spending, credit commitments and the borrowing amount requested.
    • Compare the product transfer and new-lender route, including fees, ERCs and any additional borrowing.
    • Allow time to answer lender questions and provide a consistent explanation of the figures.

    Frequently asked questions

    How long can a complex-income remortgage take from application to completion?

    Manual underwriting can take 2–6 weeks from a full application to an offer when documents are supplied promptly and there are no complications, as outlined in the underwriting guidance. Completion takes place after the offer and can take longer depending on the legal and lender processes involved.

    Can I remortgage while I am in a probationary period at work?

    A probationary period does not produce one outcome across all lenders; the employment terms and wider affordability assessment matter. Be ready to explain your start date, contract and probation status if the lender asks for clarification.

    Can I remortgage while on maternity or parental leave?

    A lender may assess income during leave alongside the confirmed terms of your return to work, but its criteria determine how those figures are treated. Evidence of leave pay and the agreed return-to-work arrangement may help explain the income position.

    Can income from renting a room to a lodger count towards affordability?

    Lender treatment of lodger income varies, and it may be assessed differently from rent received from a separate property. Ask whether the lender includes income from your specific arrangement and what evidence it requires.

    Will applying for a remortgage affect my credit score?

    A lender may review your creditworthiness as part of underwriting, and an application can involve a credit search. The effect depends on the search process and how it is recorded, so ask the lender what type of search it will carry out before submitting a full application.

    Your home may be repossessed if you do not keep up repayments on your mortgage. Mortgage advice is provided by Hayden Richards, CeMAP-qualified, as a Registered Individual of Marklay Mortgages Ltd, authorised and regulated by the FCA (FRN 930490).

    Related guides: The Specialist Mortgage Adviser’s Guide to Complex Income · Finding Lenders Who Understand Complex IT Contractor Pay Structures in 2026

  • Inside IR35 Mortgage: How It Affects Borrowing Capacity (2026 Guide)

    Inside IR35 Mortgage: How It Affects Borrowing Capacity (2026 Guide)

    Inside IR35 Mortgage: How It Affects Your Borrowing Capacity (2026 Guide)

    Applying for an inside IR35 mortgage directly affects how UK lenders calculate your borrowing capacity, rather than your eligibility. High-street lenders assess net umbrella payslip income after statutory employment deductions. Conversely, specialist lenders assessing an inside IR35 mortgage annualise gross contract day rates, which can significantly increase borrowing power. All applications remain subject to underwriting and status.

    Inside IR35 mortgage affordability assessment paperwork and contractor day rate calculations on desk
    Inside IR35 mortgage affordability is determined by whether an underwriter uses net umbrella pay or annualised day rates.

    How Do UK Lenders Assess an Inside IR35 Mortgage?

    Securing an inside IR35 mortgage involves navigating how your earnings are paid and evidenced, rather than proving whether you qualify. In the UK, mortgage providers evaluate inside-IR35 applicants through one of two distinct routes: standard employment payslip assessment or specialist contract-based underwriting.

    The HMRC off-payroll working rules on GOV.UK establish tax status and deemed employment for contractors. However, HMRC rules do not dictate how mortgage underwriters determine affordability. The Prudential Regulation Authority (PRA) and the FCA MCOB responsible lending standards require providers to ensure borrowing is sustainable, leaving specific calculation models to individual lender criteria.

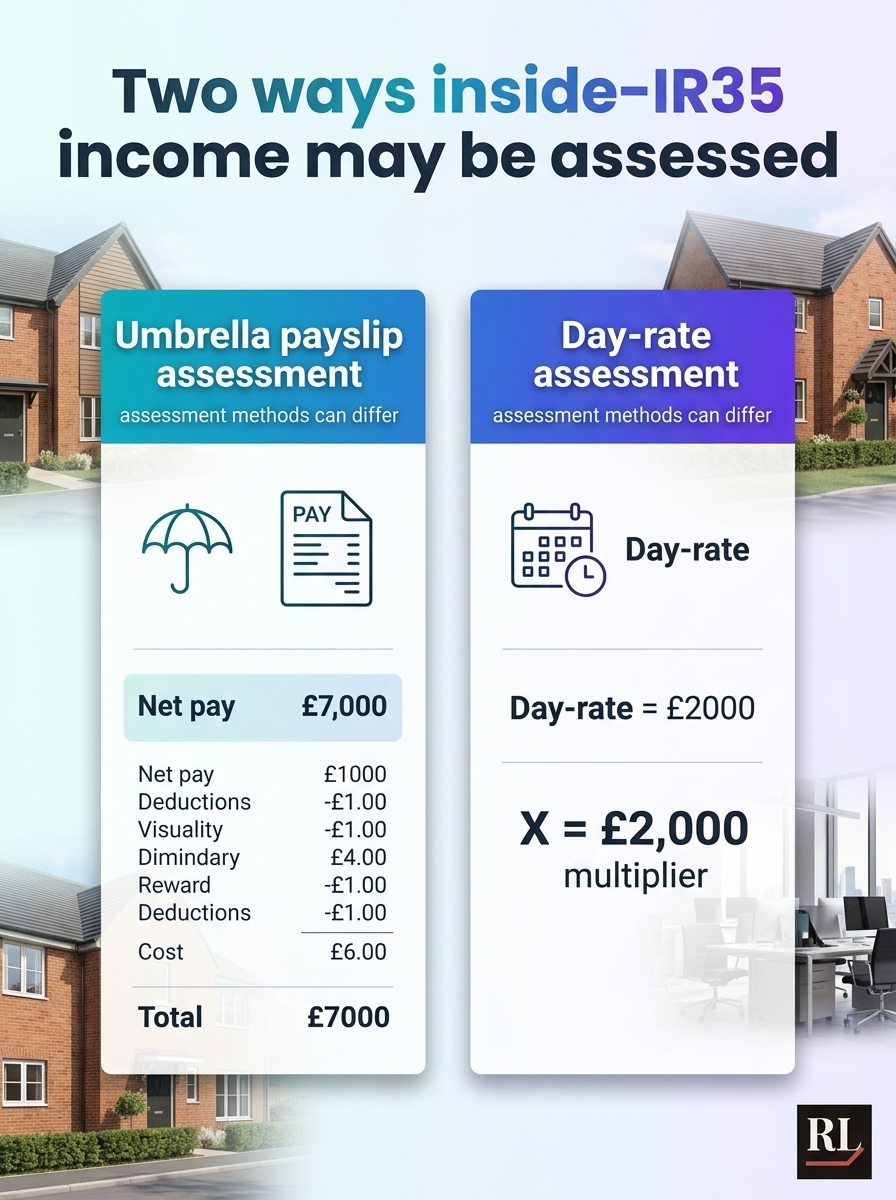
    Mainstream high-street lenders typically treat you as a fixed-term employee or agency worker. They assess the net pay figures reported on umbrella payslips. Because umbrella deductions reduce your visible net salary, this route frequently leads to a compressed borrowing figure.

    By contrast, specialist contractor lenders evaluate your application as an independent professional. They look past the payroll mechanics to calculate an inside IR35 mortgage using the gross contract assignment value. For further context on contract criteria, see our dedicated guide to IR35 contractor mortgages.

    Why Does Umbrella Net Pay Reduce Inside IR35 Mortgage Borrowing Capacity?

    When working through an umbrella company, your top-line invoice amount is the assignment rate. Crucially, this rate does not represent pure personal salary.

    Before your taxable pay is calculated, statutory employer costs are deducted from the assignment rate. These include Employer National Insurance Contributions (NICs), the Apprenticeship Levy, and the umbrella margin fee. Only after these deductions are made are employee NICs, PAYE income tax, and pension contributions subtracted from your taxable pay.

    High-street mortgage calculators input the net or basic taxable pay shown on umbrella payslips. They do not recognise that the contract rate was structured to absorb employment overheads. Consequently, an inside IR35 mortgage assessed on the high street is calculated against an artificially suppressed baseline.

    To understand how umbrella deductions are treated by underwriters, consult our umbrella company mortgage FAQ.

    How Does Day-Rate Underwriting Work for an Inside IR35 Mortgage?

    Specialist contractor underwriting determines your inside IR35 mortgage borrowing capacity using the top-line gross contract rate rather than net payslips. Lenders in this sector convert your agreed day rate into an annualised gross income figure.

    The established industry formula takes your day rate, multiplies it by the contracted days per week (typically five), and then multiplies by a standard working year, commonly 46 or 48 weeks. This standard deduction builds in allowance for unpaid annual leave and expected gaps between projects.

    For example, a contractor earning £500 per day over five days per week across 46 weeks is assessed as having an annualised gross income of £115,000. Specialist lenders apply standard borrowing multiples (typically 4.5 times income) directly to this gross figure, subject to credit score and personal liabilities.

    This underwriting methodology ensures your genuine earning capability is reflected when applying for an inside IR35 mortgage. You can explore contractor affordability mechanics in our contractor mortgage guide and our day-rate contractor FAQ.

    Comparison: Umbrella Payslip vs Day-Rate Multiplier Routes

    Assessment Factor High-Street Umbrella Route Specialist Day-Rate Multiplier Route
    Income Baseline Net or basic taxable pay from umbrella payslips. Gross contract day rate annualised across 46–48 weeks.
    Borrowing Capacity Impact Compressed borrowing limit due to employer taxes and fees. Substantially higher borrowing power reflecting gross earnings.
    Contract Requirements Standard employment proof; contract may be treated as fixed-term. Formal contract showing day rate and minimum remaining term.
    Track Record Needed Typically 3 to 6 months of continuous payslips. Usually 12 to 24 months of continuous contracting history.
    Comparison of umbrella payslip assessment vs day rate multiplier assessment for inside IR35 mortgages

    What Documents Are Required for an Inside IR35 Mortgage Application?

    Packaging an inside IR35 mortgage application requires clear documentation reconciling both your contractual terms and payroll receipts. Thorough evidence preparation prevents underwriting delays.

    To qualify for a day-rate calculation, you must provide your current signed contract detailing the day rate, start date, and contracted hours. If the assignment has under six weeks remaining, an extension letter or email confirmation from your end client or agency is generally necessary.

    Specialist lenders will also request your last three months of consecutive umbrella payslips together with matching bank statements. This allows underwriters to verify that contract billing aligns with actual deposits.

    If you recently switched from an outside-IR35 limited company to an inside-IR35 assignment, submit your previous company accounts and SA302 calculations. This documents uninterrupted career continuity in your sector.

    Modern British townhouse with mortgage worksheet on window desk for inside IR35 contractor home purchase
    Contract continuity allows inside IR35 contractors to secure high-value residential mortgages across the UK market.

    Can Gaps Between Contracts Affect an Inside IR35 Mortgage?

    Contract continuity is a primary consideration for underwriters assessing an inside IR35 mortgage. Planned gaps between contracts for holidays or professional development are standard practice and widely accepted within limits.

    Most specialist mortgage lenders comfortably accommodate assignment gaps of up to four to six weeks. For gaps exceeding eight weeks, underwriters examine your broader sector experience, accumulated savings reserves, and ongoing market demand for your skillset.

    A proven track record of twelve to twenty-four months in contracting reassures lenders that gaps are voluntary. Applying while an active contract is in place ensures the strongest borrowing assessment.

    Frequently Asked Questions

    Does changing from outside to inside IR35 affect a remortgage?

    Switching from an outside IR35 limited company to an inside IR35 umbrella contract changes the documentary evidence required. A straightforward product transfer with your existing lender rarely triggers fresh affordability checks. However, remortgaging to a new lender or raising extra capital requires a full reassessment based on current contract or umbrella terms.

    Can umbrella company pension contributions reduce mortgage borrowing?

    Salary-sacrifice pension contributions reduce the taxable net pay displayed on umbrella payslips. On high-street affordability models, this lower net income directly restricts borrowing. Specialist lenders assessing an inside IR35 mortgage calculate affordability before pension deductions, protecting your borrowing capacity.

    How soon after starting an inside IR35 contract can I apply?

    Specialist lenders can consider an inside IR35 mortgage application immediately upon signing a new contract, provided you have at least twelve months of continuous contracting history in the same profession. High-street lenders typically require a minimum of three consecutive months of umbrella payslips before considering an application.

    Can a joint applicant’s salary be combined with inside IR35 day-rate income?

    Yes. Specialist lenders regularly assess joint applications where one borrower is an inside IR35 contractor and the other is an employed or self-employed earner. The contractor’s day rate is annualised, the secondary applicant’s verified income is added, and household commitments are subtracted to determine joint borrowing capacity.

    YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.

    The guides and articles on this website are provided for general information only. They are not tailored to your personal circumstances and should not be treated as financial advice or a personal recommendation. If you would like advice based on your individual circumstances, please speak to an adviser.

    Mortgage advice is provided by Hayden Richards, CeMAP-qualified, as a Registered Individual of Marklay Mortgages Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 930490). Richards & Logic is a trading style of MarketMedia Ltd (registered in England and Wales, 07765565).

  • Mortgage Evidence Checklist for Directors of Limited Companies

    Mortgage Evidence Checklist for Directors of Limited Companies

    A mortgage evidence checklist for directors of limited companies should separate your personal income from your company’s financial position. Lenders assess salary, dividends, business performance and deposit funds in different ways, so each figure needs evidence that shows where it came from.

    Close view of neatly arranged salary slips, dividend statements and company accounts on a navy desk, with figures softly out

    Mortgage Evidence Checklist: Key Points to Prepare

    Question Evidence to organise
    Can a limited company director apply for a mortgage? Yes. Lenders assess the applicant’s personal income and may consider company performance under their own criteria.
    How do you show salary and dividends? Use payslips and a P60 for salary where applicable, plus dividend vouchers and personal bank statements for dividends received.
    Which tax records may be requested? An SA302 tax calculation and Tax Year Overview for the relevant tax years.
    What shows company performance? Company accounts and, where requested, corporation tax records. Business bank statements provide additional context.
    What counts as proof of deposit? Personal statements and other records that trace the funds back to their source, with additional evidence where funds are gifted or come from a company transaction.
    Do all lenders ask for the same documents? No. Required periods, formats and income assessment methods vary by lender and by the details of the case.
    Mortgage evidence checklist for directors of limited companies, showing documents to prepare for a mortgage application

    This infographic outlines the evidence limited company directors may need to prepare for a mortgage application. Use the checklist to organise key documents before applying.

    Which personal and business bank statements should you prepare?

    Prepare the personal and business bank statements requested for your case. The period, file format and level of detail required vary by lender, so an old document pack from another application may not meet the current criteria.

    Personal bank statements help show salary and dividends received, savings built up for the deposit, and regular financial commitments. Business bank statements show trading receipts and cash flow, helping an underwriter understand how the company operates.

    Keep company and personal transactions distinguishable. If money moves between the accounts, be ready to explain the reason and provide supporting records, so a transfer is not mistaken for salary, a dividend or additional personal income.

    For a case involving company income, our Director Logic Check and limited company director mortgage information explain how lenders may assess a director’s personal income alongside company performance.

    A modern British townhouse seen through an office window, with a mortgage application folder and deposit statements on the

    How do you prove salary, dividends and taxable income?

    Use payslips and a P60, where applicable, to evidence salary. For dividends, match dividend vouchers showing what was declared with personal bank statements showing what was paid to you.

    An SA302 tax calculation and Tax Year Overview provide evidence about your personal taxable income and HMRC tax-account information for the relevant years. They do not set out the company’s full cash flow, so they are not a substitute for company accounts or business statements.

    You can usually obtain tax calculations and overviews through your HMRC online account or by asking your accountant. Check that the records cover the tax years the lender has requested.

    A director loan repayment should be kept separate from salary and dividends. It is not automatically taxable personal income, so explain the transaction with relevant company records and bank statements rather than presenting it as earnings.

    Lenders may assess a director using salary and dividends, a share of company profits or another method under their own criteria. The Director Logic Check analyses salary, dividends and company performance against lender criteria using your latest accounts or estimates, which helps identify how the income evidence may be read.

    For more detail on the distinction between these income types, see our guide to director salary and dividend evidence.

    Which company records evidence trading history and retained profits?

    Prepare the company accounts requested for the relevant accounting periods, together with corporation tax records where requested. Lenders differ on how many accounting periods they want and whether accounts need to be finalised, signed or prepared in a particular way.

    Provide records showing your role and shareholding when requested. Ownership can affect how a lender assesses the company’s profits and which share of those profits may be considered in a personal mortgage application.

    Retained profit belongs to the company unless and until it is made available to you. Lenders differ in whether and how they consider retained profits, so do not treat them as personal income by default.

    Company bank statements add context to turnover and cash flow, but they do not replace requested accounts or tax evidence. For a closer look at the distinction, read our guide to mortgages involving director retained profits and the retained profit evidence questions and answers.

    What evidence can help if accounts are incomplete or trading is recent?

    If the company is newly established or has not completed a full accounting period, organise available management accounts, company bank statements and a clear timeline of trading. Lenders decide which evidence they can accept for a short trading history or incomplete accounts.

    An accountant’s reference letter, certificate or income forecast may help explain current performance or a recent change. Its format and usefulness depend on lender criteria, so it should support the accounts and other business records rather than stand in for documents the lender has requested.

    For contract-based work, collect contracts, renewal evidence, invoices and company records showing how the work is paid. A limited company director is not the same as a sole trader or a day-rate contractor, and the evidence should reflect the actual business and payment arrangement.

    Where a company has made a loss or income has changed, prepare a concise explanation supported by accounts and current business records. Separate a one-off event from ongoing performance so the underwriter can assess what has changed and whether it continues to affect the business.

    The Limited Company Director Mortgage service covers matching UK directors with lenders that may assess income using salary and dividends, net profit share or retained profits. For cases where only a short trading record is available, read the guide to mortgages with one year of accounts.

    Day-rate arrangements call for evidence that reflects the contract and payment structure. Our day-rate contractor mortgage questions and answers explain the distinction between contract-based evidence and a director’s company income records.

    A laptop displaying a generic company accounts spreadsheet beside printed business statements on a clean grey office desk

    How do you evidence your deposit, identity and existing commitments?

    Prepare proof of identity and address for each applicant using documents that meet the lender’s current requirements. Names and addresses should be consistent across the application and supporting records, or any difference should be explained.

    To evidence a deposit, trace the funds from their source through relevant statements or records. If someone is gifting money, the lender may ask for a gift declaration and evidence about the donor and the source of the funds.

    List existing credit commitments and provide the statements or agreements requested. These records allow regular repayments to be considered as part of the affordability assessment.

    If the deposit includes money transferred from the company, provide records explaining the transaction and its treatment. Company cash does not become personal funds simply because it appears in a personal account.

    How can you check the evidence is consistent before applying?

    Compare names, addresses, company details, accounting periods and income figures across company accounts, HMRC records and bank statements. Explain legitimate differences, such as a change in trading name or a payment made in a different period, instead of leaving the discrepancy for the underwriter to interpret.

    Label documents clearly as draft or final. Establish whether the lender requires signed accounts, a particular tax year or a specific file format before you submit the application.

    Ask the chosen lender or a qualified broker which documents, periods and formats apply to your circumstances. This check is especially important after a change in business structure or where accounts are incomplete.

    The Complex Income Eligibility Audit, known as the Logic Check, is a structured feasibility assessment rather than a rate comparison tool. For answers to common director application questions, see the limited company director mortgage FAQ.

    Related evidence routes for other income arrangements

    If your application also involves another form of income or a different business structure, use the relevant evidence route rather than treating every applicant as a limited company director.

    A contemporary British home at dusk beyond a glass meeting-room table, where a document checklist and company financial

    Frequently asked questions

    Can I use a director’s loan repayment as my mortgage deposit?

    Keep the director’s loan account entry and the matching bank transfer record together, so the source of the deposit is easy to trace.

    If I apply jointly with an employed partner, what income documents will they need to provide?

    Have them prepare their own employment records as a separate set from your company documents.

    Can a mortgage lender ask for further evidence after I have submitted my application?

    Yes. An underwriter may request clarification or updated documents after reviewing the application, particularly where a transaction or figure needs further explanation. A request is not, by itself, a final decision on the case.

    Does a limited company director apply for a mortgage as self-employed?

    Lenders may classify a director as self-employed for income assessment, but the company’s legal structure and the director’s role still matter. The lender’s criteria determine which income method and supporting documents apply.

    Do all company directors have to be named on the mortgage application?

    No, the application is made by the person or people seeking the mortgage, not automatically by every director of the company. A lender may still ask for information about the company or other owners when assessing the applicant’s share of its income.

    What if my company’s accounting year does not match the tax year?

    Keep both accounting periods clearly identified and avoid presenting figures from different periods as though they cover the same dates. A concise reconciliation from your accountant can help explain how company results relate to the personal tax records being considered.

    Conclusion

    A complete mortgage evidence checklist for directors of limited companies connects personal income, company performance, deposit funds and identity without treating them as interchangeable. Prepare each record for the purpose it serves, explain differences clearly and confirm the chosen lender’s requirements before submission.

    Your home may be repossessed if you do not keep up repayments on your mortgage. Mortgage advice is provided by Hayden Richards, CeMAP-qualified, as a Registered Individual of Marklay Mortgages Ltd, authorised and regulated by the FCA (FRN 930490).

    Related guides: Specialist Director Mortgage Broker Guide for Limited Company Directors in 2026 · Top Mortgage Options for Professional Contractors and Consultants in 2026
  • Sole Trader vs Limited Company: Does It Change How Much I Can Borrow? A 2027 Guide

    Sole Trader vs Limited Company: Does It Change How Much I Can Borrow? A 2027 Guide

    As a sole trader, your mortgage borrowing capacity depends heavily on how lenders assess your income stability and tax records. This 2027 guide explores whether incorporating as a limited company could unlock better rates and higher loan amounts.

    Sole Trader vs Limited Company: Does It Change How Much I Can Borrow? For 2027 planning, the short answer is that your business structure can change how a lender assesses your income, but it does not set your borrowing figure by itself. Lenders assess eligible income alongside your household commitments and their own criteria.

    Key points to know

    • Does a business structure set your borrowing amount? No. Lenders assess personal affordability using income they accept and their own criteria.
    • What income may a sole trader use? Lenders commonly start with net profit, supported by tax calculations and accounts.
    • How may a director’s income be assessed? A lender may use salary and dividends, or a different calculation that considers an eligible share of company profits.
    • Do company profits count as personal income? Not automatically. Company money and a director’s personal income are distinct.
    • Why can borrowing differ between lenders? Lenders use different income methods and consider household circumstances, evidence and credit history.
    • Where can you compare lender methods? Our guide to how UK lenders assess complex income compares approaches to income types including sole-trader profit, dividends and retained profits.
    • How are salary and dividends treated? Our guide to director salary and dividend assessments explains the evidence lenders may consider.

    Does your business structure affect mortgage borrowing?

    Short answer: It affects how lenders may calculate eligible income, but being a sole trader or a limited company director does not, on its own, decide how much you can borrow. Lenders assess personal affordability using the income they accept, together with their criteria for the case.

    A sole trader and their business are not separate legal persons. A limited company is a separate legal entity, so its finances belong to the company and a director’s personal income is a different figure.

    Neither turnover nor company profit should be treated as a personal income figure without considering how it is calculated and who can use it. A sole trader’s turnover is not their taxable net profit, and a limited company’s turnover or profits do not automatically become the director’s personal income.

    Business structure Income lenders commonly assess Evidence that may be relevant Why the approach can differ
    Sole trader Net profit, rather than turnover Tax calculations, tax year overviews and business accounts The business’s profit is closely linked to the proprietor’s taxable income, but lenders apply their own rules to profit history.
    Limited company director Salary and dividends, or an eligible share of company profit under some lender methods Personal income records and company accounts The company is separate from the director, and access to its profits depends on the company position, shareholding and lender criteria.
    Infographic comparing how lenders assess income for sole traders and limited company directors when borrowing.

    See how lenders may assess income differently for sole traders and limited company directors. The comparison explains why business structure can affect how much you can borrow.

    How do lenders usually assess a sole trader’s income?

    Lenders commonly start with a sole trader’s net profit, rather than gross turnover, because profit reflects business income after allowable business expenses. Tax calculations and accounts can help evidence the declared figures.

    Some lenders assess an average of recent profits, while others may give more weight to the latest year. Criteria vary, so the same accounts can produce different eligible income figures with different lenders.

    A falling or irregular profit trend may lead a lender to examine the reasons, the trading position and any supporting evidence more closely. A strong earlier year does not necessarily cancel out a more recent decline in the lender’s calculation.

    That profit-based assessment is distinct from a day-rate contractor assessment. A lender assessing a contractor may use contract and day-rate evidence under a different method rather than treating the applicant as a sole trader with annual net profit.

    For questions about sole-trader eligibility, income calculations, account history and application documents, see our sole trader mortgage guide. It also explains how lenders may approach borrowing capacity using the applicant’s circumstances and evidence.

    What income can a limited company director use?

    A lender may assess a director using salary and dividends, with the combination and supporting records it accepts varying by lender. Payslips, dividend records and personal tax documents can help show what the director has received personally.

    Company net profit is not automatically the director’s personal income. The company’s financial position, the director’s shareholding and the lender’s criteria can affect whether a calculation based on company profits is considered.

    Retained profits are money left in the company rather than paid to the director. Some lenders may take an appropriate share into account, but they assess this differently from personal salary and dividends and may require evidence of the company’s finances.

    The Director Logic Check analyses salary, dividends and company performance against lender criteria. You can bring your latest accounts or work from estimates, making it relevant when the director’s personal income does not show the full picture of the business.

    For a closer explanation of when retained profits may be considered, read our guide to using company retained profits in a mortgage assessment. Lenders still assess the company position and the director’s circumstances under their own rules.

    Why can two applicants with similar businesses borrow different amounts?

    Income is only one part of a household affordability assessment. Lenders typically consider regular household spending, existing credit commitments, dependants and other financial responsibilities alongside the income they accept.

    The deposit, requested mortgage term and repayment basis can also affect the calculation, subject to lender criteria. Repayment and interest-only mortgages work differently: with repayment, the monthly payment includes capital and interest, while interest-only payments cover interest and require a separate plan for repaying the capital.

    Credit history and the consistency of income evidence may also influence an assessment. For example, clear records that support a stable income pattern give a lender a different evidence picture from figures that fluctuate or are difficult to reconcile.

    Income multiples and affordability methods are lender-specific, not universal rules. Two applicants with similar businesses may therefore receive different borrowing assessments because their income calculation, commitments, evidence or lender criteria differ.

    What evidence can help a lender assess your income?

    For a sole trader, lenders may ask for tax calculations, tax year overviews and business accounts to evidence declared profits. Personal and business bank statements may help explain how trading income moves through the business.

    For a company director, separate personal income records from company accounts. Payslips and dividend records can evidence personal income, while company accounts show trading performance and the position of the business.

    • Sole trader records: tax calculations, tax year overviews and business accounts.
    • Director’s personal income: payslips, dividend records and personal tax documents.
    • Company performance: company accounts and, where relevant, supporting business records.
    • Additional context: lenders may ask for further documents if income has changed, accounts are recent or the business structure has changed.

    This list is illustrative. The documents and trading history a lender accepts depend on its criteria and the details of the case.

    Our Self-Employed Mortgages service covers sole traders, limited company directors and contractors, with options assessed against lender criteria for complex income. It suits applicants who need the income structure and business evidence considered together.

    For more on the documents used across different self-employed cases, see our self-employed mortgage questions and answers. If your trading history is short, our guide to mortgages with one year of accounts explains why a lender’s criteria and the wider evidence matter.

    How can you compare lender approaches before applying in 2027?

    Compare lenders using the income structure you actually have, rather than relying on a headline borrowing estimate. Ask how each lender treats recent profit trends, salary, dividends and any retained profits that may be relevant to your case.

    • Does the lender use an average of recent profit figures or focus on the latest year?
    • For a director, does it assess salary and dividends, or can it consider a share of company profits?
    • What records does it require to support fluctuating income or retained profits?
    • How does it account for your household commitments and the requested mortgage structure?

    Our limited company director mortgage guide covers common questions about director income, company accounts and retained profits. It can help frame the points to compare where personal drawings do not reflect the whole company position.

    An Agreement in Principle (AIP) is an initial indication based on the information supplied. It is not a full mortgage offer: the lender assesses the application and supporting evidence before deciding whether to make an offer and on what terms.

    An AIP or early affordability estimate does not fix the final borrowing amount. Verified income, lender criteria and the full assessment can change the outcome, so treat an early figure as an indication rather than a confirmed offer.

    Frequently asked questions

    Can I apply for a mortgage jointly with a partner who has employed income?

    Yes, a lender can assess a joint application that combines self-employed and employed income. Both applicants’ financial positions matter, and joint borrowers typically share responsibility for the mortgage debt.

    Could changing from sole trader to limited company shortly before applying affect a mortgage assessment?

    It can, because incorporation changes the legal business structure and the way income is recorded. A lender may need to understand whether the new company continues the same trade and how the earlier sole-trader accounts relate to the director’s current income.

    Does an Agreement in Principle confirm the amount a lender will ultimately offer?

    No. An AIP is an initial indication, and property valuation or full underwriting can affect whether a formal offer follows and the amount offered. It does not reserve funds for a particular purchase.

    Can business debts or personal guarantees affect mortgage affordability?

    Business borrowing may affect the company’s profit and the income a director can draw, while personal guarantees can create a potential personal liability. A lender may ask for details to understand the effect on the applicant’s finances.

    Can a director use retained profits if they own only part of the company?

    Some lenders may assess only a share of company profits that relates to the director’s ownership or control. The method and evidence requirements vary, and the company’s liabilities and financial position can also matter.

    Can I get a mortgage with only one year of self-employed accounts?

    Some lenders may consider a shorter trading history where the wider case supports it, but the evidence they accept varies. Continuity in the same trade, current business performance and the applicant’s previous experience can all help explain the figures.

    Conclusion

    Sole Trader vs Limited Company: Does It Change How Much I Can Borrow? It can change which income figures a lender considers, but the business structure alone does not determine borrowing capacity. For 2027 planning, compare how lenders treat your actual profit, personal income, household commitments and supporting evidence before relying on an early estimate.

    Your home may be repossessed if you do not keep up repayments on your mortgage. Mortgage advice is provided by Hayden Richards, CeMAP-qualified, as a Registered Individual of Marklay Mortgages Ltd, authorised and regulated by the FCA (FRN 930490).

  • How do UK lenders assess a first-time buyer with complex income?

    How do UK lenders assess a first-time buyer with complex income?

    In the United Kingdom, a first-time buyer with complex income is assessed on two fronts at once. The lender must verify non-standard earnings, such as a short self-employed record, and accept a buyer with no mortgage history. Deposit size and source also carry more weight. Specialist lenders assess these cases manually, subject to status, valuation and underwriting.

    Hayden Richards, CeMAP — Senior Mortgage & Protection Adviser
    Last reviewed: 17 September 2026
    Written for: The One-Year-Accounts Applicant

    Why is a first-time buyer with complex income harder to assess?

    A first-time buyer with a salaried job fits standard lending rules well. So does an established self-employed homeowner moving house. The difficulty comes when both unfamiliar factors sit in the same application.

    A lender assessing complex income — earnings that do not follow a simple PAYE pattern — looks for a track record. A first-time buyer has no mortgage track record to offer. Each gap makes the other harder to look past.

    Many first-time buyers with complex income are also early in their working pattern. Someone who moved from employment to self-employment recently may have both a short trading history and no prior mortgage.

    Why does a short trading history matter so much?

    Self-employed income is usually evidenced through tax records. The key document is the SA302, with its matching tax year overview. An SA302 is the tax calculation HMRC produces from a Self Assessment return. HMRC explains how to obtain these on its SA302 guidance page.

    Many mainstream lenders ask for two or more years of this evidence. With only one year, the application falls outside their rules before affordability is considered. The lender is not doubting the income. Its rules simply cannot assess it.

    Some specialist lenders will consider one year of accounts. They typically look for continuity with previous work, such as the same trade carried on as an employee. Our page on mortgages with one year of accounts covers that assessment in more detail.

    How does having no mortgage history affect the assessment?

    A homeowner remortgaging or moving has a record of mortgage payments. That record is strong evidence of how they manage a secured debt. A first-time buyer cannot provide it.

    Lenders instead rely on the wider credit file held by UK credit reference agencies: Experian, Equifax and TransUnion. Rent, utility, credit card and loan conduct all contribute. A thin file, with few accounts, gives an underwriter less to work from.

    A thin file is not the same as a poor one. It can, however, narrow the lenders willing to combine it with non-standard income.

    Why do deposit size and source carry more weight?

    Loan to value is the loan as a proportion of the property’s value. First-time buyers often borrow at higher loan to value, because their deposit has come from savings rather than equity.

    Specialist criteria for complex income tend to be widest at lower loan to value. As the deposit shrinks, fewer lenders offer products for non-standard income. A larger deposit does not remove the income question, but it can widen the lender pool.

    The source of the deposit is checked as well. UK anti-money laundering rules require lenders to verify where the funds came from. Savings need a visible trail, and a gifted deposit usually needs a signed letter confirming it is not a loan.

    Affordability evidence files for a first-time buyer with complex income

    How do the main types of complex income compare for a first-time buyer?

    The table below sets out, in general terms, where each income type tends to meet friction. Criteria differ between lenders, so this describes common patterns rather than fixed rules.

    Income type Common friction point Evidence usually requested Constraint to weigh
    Newly self-employed sole trader Short trading record SA302s, tax year overviews, accountant’s reference Smaller lender pool with one year of figures
    Limited company director Low salary and retained profit SA302s, company accounts, accountant’s reference Profit-based lenders are fewer and may ask for more documents
    Day-rate contractor Contract length and gaps between contracts Current contract, contract history, bank statements Some lenders annualise the day rate, others use tax records
    Mixed employed and self-employed One stream may be discounted Payslips plus self-employed tax records The weaker stream can limit the combined assessment
    Foreign currency income Exchange rate risk and verification Overseas payslips or accounts, bank statements, residency evidence Lenders may reduce the income figure to allow for currency movement

    How does manual underwriting help in these cases?

    Manual underwriting means a person reviews the application rather than an automated rule alone. It suits cases where the evidence needs reading in context.

    An underwriter can weigh a short trading record against prior experience in the same field. They can review a thin credit file alongside consistent rent payments. Automated systems generally cannot make those judgements.

    Manual review is not a softer standard. It is usually slower, and it often involves more questions and more documents. The general mechanics are covered in our mortgage underwriting FAQ.

    What are the trade-offs of specialist lending for a first-time buyer?

    Specialist criteria can make an application assessable where mainstream rules cannot. That benefit comes with constraints.

    • Narrower choice. Fewer lenders assess complex income at higher loan to value.
    • Potential added cost. Some lenders in this segment price for the extra assessment work.
    • Longer timescales. Manual review and additional evidence usually add time to an application.
    • Heavier documentation. Tax records, accounts, deposit trail and identity checks all need to be consistent.

    A decline from one lender is not a decline from all. Each lender applies its own criteria, and a case outside one set of rules may sit within another. For a wider view of how income types are assessed, see complex income mortgages.

    Frequently asked questions

    Can a first-time buyer be self-employed with only one year of accounts?

    Some specialist lenders consider one year of accounts, including for first-time buyers. They usually look for continuity with earlier work in the same field and a clear credit file. Many mainstream lenders ask for a longer record. With one year of figures, the lender pool is narrower, and deposit size can further limit it.

    Do lenders treat first-time buyers with complex income differently from home movers?

    Income is assessed in much the same way. The difference is the supporting evidence. A home mover has mortgage payment history and usually equity for a deposit. A first-time buyer relies on the wider credit file and on savings or a gift. That can reduce the lenders willing to accept the combination.

    Is a gifted deposit accepted alongside complex income?

    Many lenders accept gifted deposits, subject to their criteria. The giver usually signs a letter confirming the money is a gift. It states that no repayment is expected and no share in the property is held. Some lenders restrict who can gift. Anti-money laundering checks apply to the giver’s funds as well as the buyer’s.

    Does a thin credit file stop an application?

    Not necessarily. A thin file has limited history rather than negative history. Lenders review what is available, such as bank accounts, credit cards and regular bills. Combined with complex income, a thin file may reduce the number of lenders willing to proceed, particularly at higher loan to value.

    Why might a larger deposit help with complex income?

    Specialist criteria for non-standard income are generally widest at lower loan to value, because the lender’s risk is lower. A larger deposit can therefore open more of the market. It does not change how income is verified, and affordability rules still apply to the amount borrowed.

    YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.

    The guides and articles on this website are provided for general information only. They are not tailored to your personal circumstances and should not be treated as financial advice or a personal recommendation. If you would like advice based on your individual circumstances, please speak to an adviser.

    Mortgage advice is provided by Hayden Richards, CeMAP-qualified, as a Registered Individual of Marklay Mortgages Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 930490). Richards & Logic is a trading style of MarketMedia Ltd (registered in England and Wales, 07765565).

  • Why does tax-efficient accounting get directors declined by high-street lenders?

    Why does tax-efficient accounting get directors declined by high-street lenders?

    In the United Kingdom, many company directors draw a low salary and dividends, leaving profit in the company. Many high-street lenders assess only that drawn income, shown on HMRC SA302s, so it can fall short of the loan requested. Some specialist lenders assess company profit instead, subject to status, valuation and underwriting.

    Hayden Richards, CeMAP — Senior Mortgage & Protection Adviser
    Last reviewed: 3 October 2026
    Written for: The Tax-Efficient Director

    What does tax-efficient accounting look like to a lender?

    A limited company director can take money out in several ways. The common pattern is a modest salary through PAYE, topped up with dividends. Any profit not needed personally stays inside the company.

    That pattern usually reflects sound tax planning agreed with an accountant. A lender reads the same figures for a different purpose. It is not asking what the business earns. It is asking what personal income it can rely on to meet repayments.

    The gap between those two questions is where many director declines start. A company can be profitable and growing, while the director’s personal income looks modest on paper.

    Company accounts and tax papers reviewed for a limited company director mortgage

    Why do many high-street lenders count only salary and dividends?

    Mainstream lenders process high volumes through automated affordability rules. Those rules are built for income that fits a standard shape. For a director, the standard shape is salary and dividends: the amounts paid to the individual in a tax year.

    Those figures come from an SA302 and the matching tax year overview. An SA302 is the tax calculation HMRC produces from a Self Assessment return. Both documents show personal income only. Profit left in the company does not appear on either.

    So if a director drew a small salary and a restrained dividend, that is the income the rules assess. The underlying strength of the business sits outside the calculation. Where the drawn figure does not cover the loan requested, the application fails affordability.

    How does retained profit change the picture?

    Retained profit is post-tax profit kept in the company rather than paid out. For a tax-efficient director, it can be a large share of what the business produces in a year.

    A lender assessing salary and dividends does not see retained profit as income. It may appear in the company accounts, but it is not money the director has received. Many mainstream lenders therefore leave it out.

    Some specialist lenders take a different view. They assess the director’s salary plus their share of the company’s net profit, whether or not it was drawn. How that works in practice is covered in more depth in our guide to how lenders treat director retained profit.

    What other accounting choices reduce assessable income?

    Low drawings are the most visible cause, but not the only one. Several ordinary decisions can lower the figures a lender works from.

    • Employer pension contributions paid by the company reduce company profit. They also bypass personal income altogether.
    • Allowable business expenses reduce net profit. Where a lender uses net profit, higher expenses mean a lower assessed figure.
    • Director’s loan account movements are money taken out that is neither salary nor dividend. Lenders generally do not treat them as income, and an overdrawn balance can raise questions.
    • Dividend timing can move income between tax years. One low year beside one high year may be averaged down, or the lower year used.
    • A deliberate reduction in drawings, perhaps to fund investment, can look like falling income to an underwriter.

    None of these choices is wrong. Each is a normal part of tax-efficient accounting, and each changes the evidence a lender sees.

    Desk with company profit charts used in a specialist lender assessment

    How do specialist lenders assess the same director differently?

    Lenders in this segment tend to rely more on manual underwriting. A person reviews the file, rather than an automated rule alone. That allows the company accounts to be read in context.

    The main difference is the income basis. The table below compares the two approaches in general terms.

    Factor Salary and dividends basis Salary plus share of net profit basis
    Income figure used Salary and dividends actually drawn in the tax year Salary plus the director’s share of post-tax company profit
    Main evidence SA302s and HMRC tax year overviews Company accounts, often with an accountant’s reference, alongside SA302s
    Effect of retained profit Not counted Counted, in proportion to shareholding
    Typical lender pool Many mainstream lenders Some specialist lenders and a smaller number of mainstream lenders
    Trade-offs Wider choice, but assessed income may be lower Narrower choice, more documents, and criteria on shareholding and trading history

    A profit-based assessment is not automatic. Underwriters still look for stable or rising profit, and may question a sharp fall between years. Shareholding matters too, because only the director’s own share of profit is counted.

    UK mortgage application file prepared with evidence of tax-efficient accounting

    What evidence do lenders ask a director for?

    Requirements vary by lender, but the core pack for a director is broadly similar.

    • SA302 tax calculations for recent tax years, with the matching tax year overviews
    • Full company accounts, usually the same versions filed at Companies House
    • An accountant’s reference or certificate confirming salary, dividends and net profit
    • Personal and sometimes business bank statements
    • Evidence of shareholding where profit is being assessed

    Filed accounts are public, and underwriters can compare them with what an application states. The company’s filing history can be checked on the government’s Companies House company information service.

    What are the trade-offs of a profit-based lender?

    Assessing net profit can produce a higher income figure. It also brings constraints that should be weighed alongside it.

    The lender pool is narrower, so product choice is more limited. Some lenders in this segment price for the added assessment work, through rates or fees. Most expect a longer trading record, and many set a minimum shareholding before profit counts.

    The document burden is also heavier. An application that relies on company profit needs accounts that are current, consistent with tax records, and explainable. For a broader view of lender criteria for directors, see mortgages for limited company directors.

    Frequently asked questions

    Does a low salary alone lead to a declined application?

    Not on its own. The decline follows when the income a lender assesses does not support the loan requested. A low salary with substantial dividends may still meet a mainstream lender’s affordability rules. The risk rises when drawings stay low and profit stays in the company. Many mainstream lenders count only what was drawn.

    Can retained profit from earlier years be counted?

    Treatment varies. Lenders using a net profit basis usually assess profit for recent accounting periods, not the full accumulated balance. Some take the latest year, others average two years, and a falling profit may lead to the lower figure being used. Accumulated reserves may support the wider case, but they are not generally treated as annual income.

    Why might a mainstream lender decline while a specialist lender accepts?

    The two lenders may be assessing different income figures from the same accounts. One counts salary and dividends drawn, the other counts salary plus a share of net profit. Neither is misreading the file. A specialist acceptance still depends on status, valuation, underwriting and the lender’s own criteria on shareholding and trading history.

    Do employer pension contributions affect mortgage affordability?

    They can. Contributions paid by the company reduce its net profit, which matters where a lender assesses profit. They do not appear as personal income, which matters where a lender assesses drawings. The effect depends on which basis the lender uses and how large the contributions are relative to profit.

    Is an accountant’s reference required?

    Many lenders assessing directors ask for one, particularly where net profit is being counted. It typically confirms salary, dividends and profit for recent periods, and is signed by a qualified accountant. Requirements differ, so some lenders rely on SA302s and filed accounts alone, while others set specific wording or qualification standards.

    For related questions on how lenders treat directors’ pay, see the salary and dividend mortgage FAQ.

    YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.

    The guides and articles on this website are provided for general information only. They are not tailored to your personal circumstances and should not be treated as financial advice or a personal recommendation. If you would like advice based on your individual circumstances, please speak to an adviser.

    Mortgage advice is provided by Hayden Richards, CeMAP-qualified, as a Registered Individual of Marklay Mortgages Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 930490). Richards & Logic is a trading style of MarketMedia Ltd (registered in England and Wales, 07765565).

  • Why does a manufacturer’s pipeline need a commercial architecture, not campaigns?

    Why does a manufacturer’s pipeline need a commercial architecture, not campaigns?

    A UK industrial manufacturer’s pipeline needs a commercial architecture because the buyer’s evaluation is continuous and campaigns are not. A tooling or machinery buying committee researches, specifies and shortlists over six to eighteen months. An architecture keeps market intelligence, qualification rules, routing and board reporting running against that cycle, so the business is present when the shortlist forms rather than when a campaign happens to be live.

    What is a commercial architecture?

    A commercial architecture is the standing system that turns engineering capability into qualified pipeline. It is not a rebrand of the marketing department. It is a set of decisions, written down and owned, that stay in force between campaigns.

    Six components make it up:

    1. Objectives. What good looks like in pipeline movement and cost discipline, stated so the board can test it.
    2. Market. The account types and buying committees the business will prioritise, and those it will not.
    3. Message. The technical and commercial case that answers the committee’s questions at each stage, from first research to procurement.
    4. Process. Qualification rules, stage-entry criteria, routing, and the hand-over standard between marketing, sales and engineering.
    5. People. Who owns each decision, and the operating rhythm that keeps them owned.
    6. Tooling. The systems that connect buyer signals to CRM actions and to the board pack.

    A campaign can sit inside this. It cannot replace it. How the components are installed as one operating system is described at how the autonomous pipeline system works.

    Why do campaigns fail against a long buying cycle?

    Campaigns are episodic by design. They are staffed for bursts, measured over weeks, and switched off when the budget line ends. The buyer’s process does not share that rhythm.

    For capital equipment or tooling, the requirement forms internally, a business case is written, specifications are checked and a first shortlist is drawn up, often before any supplier is aware. When a campaign runs, it reaches whichever accounts happen to be researching during its window. When it stops, the accounts that start researching the following month meet silence.

    Three failure patterns follow:

    • Late arrival. The business becomes visible after the shortlist has closed, and is asked to quote as a benchmark rather than a contender.
    • Activity without qualification. The campaign produces enquiries, but nobody has written down what makes an enquiry worth engineering time, so the sales team sorts by instinct.
    • Reporting drift. The board is shown what the campaign measured, such as impressions and enquiry counts, because that is what exists, and pipeline velocity is never on the page.

    None of these is fixed by running the next campaign harder.

    What does an architecture change in practice?

    AreaCampaign modelCommercial architecture
    TimingBursts on the marketing calendarAlways on, aligned to the buyer’s evaluation window
    Demand captureEnquiry forms and event scansBuyer intent signals mapped to accounts and stages
    QualificationJudged case by case by whoever picks up the leadWritten stage-entry criteria applied the same way every time
    Hand-overMarketing passes leads to salesRouting rules move accounts to technical follow-up when evidence is present
    MeasurementOutputs: impressions, clicks, enquiries, badge scansMovement: stage time, conversion between stages, cost per qualified opportunity
    Board viewActivity reportPipeline velocity and cost per acquisition
    Budget logicChannel mixSystem components, funded in order of dependency

    How does intent data fit?

    Buyer intent data is demand-side research signal: evidence that an account is investigating a product category before it contacts a supplier. It is the input that lets the architecture run continuously instead of waiting for an enquiry.

    It is only useful inside the process component. A feed of in-market accounts with no stage-entry criteria and no routing is a longer list that ages badly. The architecture gives the signal somewhere to go: a written definition of what counts as sales-ready, and a rule for who acts on it and how quickly.

    Two boundaries keep it honest. Intent data is not shipment tracking, customs records or any other description of goods already moving, which say nothing about a buyer’s readiness. See buyer intent data versus shipment tracking. And the provider is the smaller decision. Choosing one is covered in how to compare intent data providers for UK industrial sectors.

    What does the board see?

    A manufacturing board does not need more marketing reporting. It needs commercial mechanics it can manage. Four lines, monthly:

    • Stage time by stage, with the trend against the previous quarter.
    • Conversion between stages, so the board can see where opportunities stall.
    • Cost per qualified opportunity, by source, so channels are judged on the same unit.
    • Cost per acquisition, the figure that connects commercial spend to signed revenue.

    Together these make up pipeline velocity: the rate at which qualified opportunities become signed revenue. When the board can see velocity, it can ask where the pipeline leaks and expect an answer in pounds and days rather than in campaign metrics.

    How do you know you need an architecture rather than another campaign?

    Three conditions, usually present together:

    1. The campaign calendar changes often and the pipeline does not. Channels are rotated, agencies are replaced, and stage time stays where it was.
    2. Qualification is subjective. Ask two salespeople what makes an enquiry qualified and get two answers. Ask for it in writing and get none.
    3. The board cannot explain leakage. The business can describe what marketing did last quarter but not where opportunities were lost or what it cost to lose them.

    Where all three hold, the next campaign will produce the same result as the last one, because the system it runs inside has not changed.

    How do you start?

    Not with tooling and not with a campaign brief. Start by writing down the current state: what signals are captured today, where they die, what “qualified” means in practice, and what the board currently sees. That baseline is the first deliverable of the architecture, and it is usually the first time the sales and marketing functions have agreed on a definition.

    CMOxpert runs this as a fixed-scope 30-day pipeline diagnosis with a written read-out of where high-margin buyers are being lost. As at September 2026 the sprint is listed at £3,500 on the pricing page, credited against the first retainer month if the engagement continues within 60 days. The read-out is the board’s evidence for whether to install the architecture, with CMOxpert or internally.

    Frequently asked questions

    What is a commercial architecture in a manufacturing business?

    It is the standing system of objectives, target market, message, process, ownership and tooling that turns engineering capability into qualified pipeline. Unlike a campaign, it stays in force between marketing activity, so the business is present throughout a six-to-eighteen-month buying cycle rather than only when a campaign is live.

    Why do marketing campaigns fail for industrial manufacturers?

    Because campaigns run in bursts and the buyer’s evaluation runs continuously. A campaign reaches accounts that happen to be researching during its window and misses those that start afterwards. Without written qualification and stage definitions, the enquiries it does produce are sorted by instinct and reported as activity rather than pipeline movement.

    Is buyer intent data the same as shipment tracking?

    No. Buyer intent data is demand-side evidence that an account is researching a product category before contacting a supplier. Shipment tracking and customs records describe goods already moving under a decision taken months earlier. Only the first can inform qualification, routing and timing of sales follow-up.

    What should a managing director track instead of enquiry volume?

    Stage time by stage, conversion between stages, cost per qualified opportunity by source, and cost per acquisition. Together these describe pipeline velocity, the rate at which qualified opportunities become signed revenue, which is the figure that connects commercial spend to the management accounts.

    Does a commercial architecture replace trade shows and campaigns?

    No. It gives them somewhere to sit. A trade show becomes an activation event for accounts the architecture has already identified as in market, and a campaign becomes a message delivered to a defined segment at a defined stage. Both are judged on cost per qualified opportunity rather than on attendance or impressions.

    Related guides: How to Compare Intent Data Providers for UK Industrial Sectors: A 2026 Comparison · Tungsten Price Pressure and the UK Tooling Sector: Why Demand Visibility Is Now a Board Issue

  • Fractional CMO or marketing manager: which does a UK manufacturer need?

    Fractional CMO or marketing manager: which does a UK manufacturer need?

    A UK industrial manufacturer needs a marketing manager when the commercial system already works and the gap is execution. It needs a fractional CMO when the gap is the system itself: qualification rules, stage definitions and board reporting on pipeline velocity. The two roles are not substitutes. The common mistake is to hire an execution role and expect it to design the architecture.

    What does each role actually own?

    The titles are used loosely in engineering businesses, so it helps to define them by what each is accountable for.

    Area Marketing manager (full-time) Fractional CMO (part-time, board-facing)
    Core remit Execution across channels: content, events, website, campaigns The commercial system: who to target, what qualifies, how it is reported
    Pipeline accountability Usually indirect, measured on activity or enquiry volume Direct, measured on qualified movement and stage time
    Relationship to sales Hands over leads Defines the hand-over standard with the sales director
    Board interaction Reports through the managing director or sales director Reports to the board on pipeline velocity and cost per acquisition
    Time to first plan Recruitment, notice period and ramp-up Weeks, because the role starts with a diagnosis rather than onboarding
    Cost structure Salary, employer National Insurance, pension, benefits, recruitment fee Fixed monthly fee, no employment overhead

    The first row is the one that matters. A marketing manager executes within a system. A fractional CMO is accountable for whether the system exists.

    Why does the distinction matter in a six-to-eighteen-month sales cycle?

    In a short-cycle business, execution volume and pipeline move together, so a good marketing manager is enough. In industrial tooling and machinery, the buying committee researches, specifies and shortlists over many months, often before any supplier is contacted. Activity that is not aligned to those stages produces enquiries without producing qualified opportunities.

    That is a design problem. It needs someone to decide which accounts are in market, what evidence moves an opportunity from evaluation to specification to procurement, and how the board sees the result. If nobody owns those decisions, the marketing manager is measured on campaigns and the sales team re-qualifies everything by hand. The board sees effort rising and pipeline velocity flat.

    The appetite is there. In the Make UK and PwC Executive Survey 2026, 37% of UK manufacturers named increased marketing as the focus of their strategy to secure growth in 2026, ahead of new products, cost control, AI investment and exporting (Make UK / PwC). The question is what that spend should buy, and who owns the answer.

    One symptom is worth checking for. If the business cannot say, in writing, what makes an opportunity qualified, the gap is architectural and no amount of execution will close it. What a qualified pipeline should look like is set out in what a qualified pipeline should deliver.

    What does each option cost?

    Salary benchmarks for marketing roles vary widely by region and sector, and most published figures come from recruiters with an interest in the number. This article does not quote one. The comparison a finance director can actually make is between cost structures.

    A full-time senior marketing hire carries salary, employer National Insurance contributions, pension contributions under auto-enrolment, benefits, a recruitment fee, and the months between the decision to hire and the point at which the person is productive. That cost is fixed whether or not pipeline moves.

    CMOxpert’s engagement terms are published. As at September 2026, the pricing page lists a fixed-scope 30-day pipeline diagnosis sprint at £3,500 and an ongoing pipeline architecture retainer from £3,000 per month, scoped from the sprint findings. The sprint fee is credited in full against the first retainer month if the client continues within 60 days.

    The point of the published structure is that the board decides in two steps. It buys a diagnosis first, sees a written read-out of where the pipeline leaks, and only then decides whether to fund the architecture. A permanent hire offers no equivalent stage gate.

    How should the board judge return?

    Any return multiple quoted before a diagnosis is invented, and this article does not offer one. The credible test is whether, within an agreed period, the role has produced four things that did not exist before.

    1. A baseline. A written account of where demand is leaking and where qualification fails, drawn from the business’s own CRM and order book.
    2. Stage mapping. Which buyer signals correspond to which stage, and what evidence moves an opportunity forward.
    3. Velocity tracking. Time in stage and conversion between stages, reported monthly against the baseline.
    4. A board cadence. Pipeline movement translated into cost per qualified opportunity and cost per acquisition, in the board pack, every month.

    If a marketing manager can deliver those four with evidence, the business does not need a fractional CMO. If not, the gap is structural, and it will persist however hard the marketing manager works.

    When is a marketing manager the right answer?

    • The business already has written qualification criteria that sales and marketing both use.
    • The board already receives pipeline velocity and cost per acquisition, and trusts the numbers.
    • The constraint is capacity: content is not being produced, events are not being worked, the website is not being maintained.
    • The sales director is willing and able to own the commercial system, and needs an execution partner rather than a strategist.

    In that situation a fractional CMO would be paid to design something that already exists.

    When is a fractional CMO the right answer?

    • Enquiries arrive, but the sales team cannot say which are worth engineering time.
    • Trade show leads and website enquiries are treated the same way as accounts showing genuine buyer intent. The difference between demand-side research signals and other data is explained in buyer intent data versus shipment tracking.
    • The board sees activity reports and asks, every quarter, what marketing is for.
    • A previous marketing manager left, or is about to, and the board is unsure whether to replace the role like for like.
    • The business cannot justify a full-time senior salary but needs senior commercial ownership now.

    Manufacturers in the West Midlands tooling and engineering corridor face a particular version of this: a long cycle, a technical buyer, and a marketing function that has historically been one person and a brochure. The regional offer is described at fractional CMO for West Midlands engineering.

    How do the two roles work together?

    In the businesses where this works best, the fractional CMO owns the commercial architecture: target market, qualification rules, routing, and board reporting. The marketing manager, or a marketing executive, owns execution inside that architecture: content calendar, event logistics, website, CRM hygiene. Neither is asked to do the other’s job.

    The sequence matters. Install the architecture first, then hire or redirect execution into it. Hiring execution first and hoping the system emerges is how most manufacturers end up with a busy marketing department and a static pipeline.

    Where a board wants to settle the question with evidence rather than opinion, the fixed-scope pipeline diagnosis produces a written read-out of where the pipeline leaks. If the read-out shows an execution gap, the recommendation will be a marketing manager. If it shows a design gap, it will not.

    Frequently asked questions

    Is a fractional CMO worth it for a UK tool or machinery manufacturer?

    It is worth it when the gap is the commercial system rather than execution: no written qualification criteria, no stage definitions, and no board reporting on pipeline velocity. Where those already exist and work, a marketing manager is the better use of the budget.

    What does a fractional CMO do that a marketing manager does not?

    A fractional CMO owns the design of the commercial system: which accounts to target, what evidence qualifies an opportunity, how it is routed to sales, and how the board sees the result. A marketing manager executes within that system. The first is accountable for pipeline movement, the second for activity.

    How much does a fractional CMO cost in the UK?

    Fees vary by provider and scope. As at September 2026, CMOxpert publishes a fixed-scope 30-day pipeline diagnosis sprint at £3,500 and a pipeline architecture retainer from £3,000 per month, with the sprint fee credited against the first retainer month if the engagement continues within 60 days.

    Can a marketing manager deliver the same result?

    Only if the role is given ownership of qualification rules and board reporting, and has the seniority to hold the sales director to a hand-over standard. In most manufacturing businesses it is not, so the pipeline gap persists regardless of how well the campaigns are run.

    What should a managing director ask for before deciding?

    A written diagnosis of where the pipeline leaks, how current qualification maps to CRM stages, and what board reporting would look like. That evidence shows whether the gap is execution or design, and it makes the hiring decision a consequence of the facts rather than a guess.

  • Trade shows or intent data: where should a UK manufacturer put a £20,000 marketing budget?

    Trade shows or intent data: where should a UK manufacturer put a £20,000 marketing budget?

    UK manufacturers face a perennial dilemma: should they invest £20,000 in physical trade shows or buyer intent data platforms? Each channel offers distinct advantages, but the right choice depends on your specific sales cycle and target audience.

    For a UK industrial tool or machinery manufacturer with £20,000 to spend, most of it belongs in always-on buyer intent capture and qualification, with trade shows kept as targeted activation for accounts already identified as in market. A stand records presence. Intent data records demand-side research. Procurement usually starts months before show season, so the budget should follow the buyer’s timeline, not the exhibition calendar.

    Why Does Buyer Intent Data Keep Coming Up?

    Exhibitions are the default line in most engineering marketing budgets because they are visible, familiar and easy to justify to a board. The stand is photographed, the badge scans are counted, and the sales team comes home with a list. The problem is what the list represents.

    A badge scan tells you that a person attended. It does not tell you whether their company is evaluating your category, how soon a decision is due, or which member of the buying committee you spoke to. For a capital equipment or tooling purchase with a six-to-eighteen-month cycle, the committee has usually formed its requirement and a first shortlist before the show opens. The stand meets buyers late.

    Intent data answers the question the stand cannot. It surfaces accounts whose research behaviour shows they are comparing specifications, requesting category information or aligning internal stakeholders, and it does so continuously rather than on two days in the year. The full argument is in why trade shows fail to capture intent before procurement starts.

    What does a trade show actually buy?

    The visible costs are stand space, build, graphics, travel, accommodation and the days the engineering and sales team spend away from customers. The hidden costs arrive afterwards.

    • Re-qualification. Every scanned contact has to be sorted into in-market, not in-market and unknown. That work lands on the sales team in the weeks after the show, when it is already behind on live quotations.
    • Follow-up latency. Leads that are not followed up within days lose whatever momentum the conversation created. The buyer’s evaluation does not pause while the stand is packed away.
    • Engineering time on the wrong accounts. A curious visitor who asks for a drawing consumes the same applications engineering hours as a buyer with an approved capital request.

    What a trade show does buy, and buys well, is face-to-face technical validation with an account that is already evaluating. That is a closing-stage asset, not a discovery engine.

    What does intent data buy?

    Buyer intent data is demand-side research signal: evidence that an account is investigating a product category before it contacts a supplier. It is not shipment tracking, customs data or any record of goods already moving, which describe transactions that were decided months earlier. The distinction matters because only the first kind of signal can be acted on before a shortlist closes. See buyer intent data versus shipment tracking.

    Spent well, intent budget buys three things:

    • Coverage. Continuous visibility of which accounts in your target segments are researching your category, across the whole year rather than at events.
    • Qualification rules. Written criteria for what counts as a sales-ready signal, so the sales team receives accounts that meet a standard rather than a list to sort.
    • Routing. A defined hand-off from signal to technical follow-up, with the latency measured.

    The provider is the smaller decision. The rules and routing are what make the data usable. How to compare providers for UK industrial sectors is covered in how to compare intent data providers.

    How do the two channels compare?

    QuestionTrade showIntent data with qualification
    What it measuresPresence at a standResearch behaviour by account
    Timing against procurementFixed dates, usually after the requirement is formedContinuous, usually before the shortlist closes
    Lead readinessMixed; sorted after the eventDefined by stage-entry criteria before hand-off
    Follow-up loadHigh, concentrated in the weeks after the showSteady, governed by routing rules
    What the board can seeScans, meetings, cost of attendanceQualified opportunities, stage time, cost per qualified opportunity
    Failure modeVolume without readinessData bought without rules to act on it
    Best useTechnical validation with accounts already in evaluationDiscovery and qualification across the year

    How should £20,000 be split?

    There is no universal percentage, and any article that gives one is guessing. The allocation follows from four decisions, in order.

    1. Fund the qualification layer first. Stage definitions, routing rules and a way to measure follow-up latency cost time more than money, but they must exist before either channel is worth funding. Without them, intent data becomes a longer list and a trade show becomes a longer spreadsheet.
    2. Buy intent coverage for the segments that matter. Coverage of the product categories and account types the business actually wants to win, not the widest feed available.
    3. Keep the one or two shows where technical validation happens. If a particular exhibition is where your buyers expect to see machines running or tooling cut, it earns its place as a closing venue. The rest of the calendar is optional.
    4. Attend with a target list. Use the intent layer to name the accounts to meet at the stand before the show opens, and measure the show on how many of those conversations happened.

    On this logic, the larger share of a £20,000 budget goes to coverage and qualification because that is the part that works every week. The show budget is sized to the number of events that genuinely close business, which for most manufacturers in this segment is small.

    What should the board see?

    A managing director does not need a report on either channel in isolation. Three lines cover both:

    • Cost per qualified opportunity, by source, so a show and the intent layer are judged on the same unit.
    • Stage time for opportunities from each source, which shows whether trade show leads take longer to convert because they arrive unqualified.
    • Follow-up latency, the days between a new signal or a stand conversation and the next technical action.

    Reported this way, the annual “should we exhibit” debate turns into a comparison of cost per qualified opportunity. That is a question the finance director can settle. The standard for what a qualified opportunity should look like is set out in what a qualified pipeline should deliver.

    How do the two channels work together?

    The working model treats intent as the engine and the exhibition as the amplifier.

    • Before the event. Identify in-market accounts from the intent layer, agree who will be invited to the stand and what technical question each meeting should answer.
    • At the event. Spend stand time on specification alignment and next-step planning with named accounts, not on educating visitors who are not evaluating.
    • After the event. Route every conversation back through the same stage-entry criteria as any other signal, so attendance does not reset qualification.

    Where a manufacturer wants an outside view of how its current lead flow maps to revenue stages before committing the budget, CMOxpert runs a fixed-scope pipeline diagnosis that identifies where demand is leaking and which channel is producing qualified movement.

    Frequently asked questions

    Are trade shows still worth it for UK industrial manufacturers?

    Yes, as a closing and technical-validation venue for accounts already in evaluation. They are a poor discovery channel because the buying committee usually forms its requirement and first shortlist before the show, so the stand meets buyers late and the leads need re-qualifying afterwards.

    How can a manufacturer identify buyer intent before a trade show?

    Use buyer intent data to surface accounts researching your category, then apply written stage-entry criteria to decide which are in market. That produces a named target list for the stand, so conversations happen with accounts that are evaluating rather than with whoever walks past.

    What is the difference between a badge scan and buyer intent?

    A badge scan records that a person attended a stand. Buyer intent is demand-side evidence that an account is researching a product category, such as comparing specifications or requesting category information. Only the second says anything about procurement readiness or timing.

    How much of a £20,000 budget should go to trade shows?

    Enough to attend the one or two events where your buyers expect technical validation, and no more. The larger share belongs in intent coverage and the qualification rules that make it usable, because that part of the system works every week rather than on fixed dates.

    Can a manufacturer run both without adding marketing headcount?

    Yes, if qualification is treated as a system rather than a campaign. Written stage-entry criteria and automated routing reduce the sorting work that trade show leads normally create, so the same team handles both channels with less re-qualification and shorter follow-up latency.

    Related guides: How to Compare Intent Data Providers for UK Industrial Sectors: A 2026 Comparison · Tungsten Price Pressure and the UK Tooling Sector: Why Demand Visibility Is Now a Board Issue